
The Real Cost of Buying in Chicagoland Starts Beyond the List Price
For Michael Wandland, buying a home in the Chicagoland area does not begin with the search. It begins with understanding what the purchase will actually cost after taxes, attorney involvement, financing, repairs, HOA expenses and long-term maintenance enter the equation. Most buyers he works with purchase between $250,000 and $700,000, with typical down payments ranging from 3% to 20%, closing costs often landing between 2% and 5%, and monthly payments commonly falling between $2,500 and $5,500 depending heavily on taxes and interest rates.
That is where Wandland’s background changes the buying process. Before real estate, he served in the U.S. Coast Guard and later worked in general contracting and residential remodeling. Today, as a Compass real estate advisor who also works as a general contractor, he helps buyers evaluate a home as both a purchase and a long-term financial commitment. The accepted offer is only one part of the deal. The taxes, condition, financing structure and ownership costs determine whether the home still makes sense after closing.
Buying in Chicagoland works best when buyers treat the purchase as a full-cost strategy, where taxes, attorney involvement, financing structure, property condition and long-term maintenance matter as much as the offer price.
The First Number Is Never the Full Number
The listing price can create a false sense of affordability in Chicago, Illinois, and the surrounding suburbs. Wandland sees buyers compare homes by purchase price, then miss the costs that shape the actual monthly and long-term ownership picture. Property taxes can vary significantly from town to town, which means two homes at similar prices can produce very different affordability outcomes.
“Many buyers focus only on the listing price and underestimate taxes, maintenance costs, HOA or renovation expenses,” Wandland said. That warning sits at the center of his process because Chicagoland buyers are often choosing between communities with different tax structures, housing ages, municipal requirements and repair profiles. A buyer may qualify for the purchase price and still feel stretched if the tax bill, association dues, insurance, deferred maintenance or near-term updates were never part of the original decision.
That is why Wandland puts the financial side of the purchase near the front of the conversation. A $500,000 home in the Chicagoland area is not just a $500,000 decision. It can involve a down payment between 3% and 20%, closing costs between 2% and 5%, and a monthly payment that moves sharply depending on the local tax burden, rate environment and property type. Those numbers are the difference between a buyer who owns comfortably and a buyer who discovers the real cost too late.
Illinois Adds Process Before the Closing Table
The mechanics of buying in Illinois add another layer to Wandland’s guidance. Illinois is primarily an attorney state, which means buyers must understand how legal review, contract terms and attorney involvement can shape the transaction before closing. Most transactions in Wandland’s market close within 30 to 45 days, but that timeline depends on financing, negotiations and the details that surface once a contract is in motion.
That structure can surprise buyers who relocate from states where title or escrow processes feel more standardized. “Many out-of-state buyers underestimate how much taxes, local ordinances, and attorney involvement can impact transactions in Illinois,” Wandland said. In the Chicagoland area, the process is not only about finding the right house and submitting a competitive offer. It also requires understanding how each suburb operates, what local requirements may affect the deal and how attorney review fits into the broader timeline.
Wandland’s strategy is to prepare buyers before they need to make fast decisions. Limited inventory across many Chicagoland suburbs continues to affect competition, and buyers who wait until the right house appears to understand financing, costs or contract expectations often lose time when speed matters. Preparation gives them a cleaner path from offer to inspection to attorney review to closing because fewer decisions are being made under pressure.
Property Condition Becomes Part of the Financial Strategy
Wandland’s contractor background gives this Market Impact Profile its clearest distinction. In a region with historic housing stock, suburban variety and many homes that may need updates, condition is not a side note. It is part of the buyer’s financial strategy.
“I also help buyers evaluate the condition of homes from a contractor’s perspective, which can help them avoid costly mistakes or identify opportunities other buyers may overlook,” Wandland said. That perspective changes how buyers interpret inspections, repairs and renovation potential. A cosmetic issue may be manageable. A hidden system concern may alter the offer strategy. A home that looks less polished online may become a better long-term play if the structure, layout and location support the buyer’s goals.
This matters because Wandland does not separate real estate advice from the practical reality of ownership. He helps buyers think through repair exposure, minor upgrades, renovation costs and long-term value before those items become expensive surprises. For investor clients, that lens can determine whether a property has enough upside to justify the project. For first-time buyers and move-up buyers, it can prevent a stretched purchase from becoming a strained ownership experience.
His approach also affects negotiations. A contractor-informed inspection review gives buyers more specific language when they ask for repairs, credits or price adjustments. Instead of reacting emotionally to a list of defects, Wandland helps them sort what matters, what can wait and what should affect the economics of the deal.
Preparation Shapes the Offer Before Competition Begins
Wandland describes the Chicagoland market as one where preparation and strategy matter more than ever. Inventory remains relatively tight across many suburbs compared with historical averages, and steady demand continues to support home values despite interest rate movement. Buyers cannot control those conditions, but they can control how prepared they are before they enter them.
“Buyers in the Chicagoland market need to understand that preparation and strategy matter more than ever,” Wandland said. For him, preparation includes lender conversations, realistic monthly payment planning, local inventory education and a clear understanding of the buyer’s tolerance for taxes, repairs and competition. It also includes knowing when not to stretch for a house that creates the wrong financial trade-off.
That guidance reflects how Wandland defines a strong agent in his market. “In today’s market, it’s not enough to simply open doors,” he said. “Clients need an advisor who understands negotiations, financing, construction concerns, market timing, and long-term wealth building through real estate.” The quote captures why his process stays anchored in cost and mechanics rather than surface-level excitement. He wants buyers to understand the deal they are making, not just the home they are touring.
That approach is especially relevant for first-time buyers, young professionals, investors and move-up buyers, the groups Wandland most often serves. Each group faces a different affordability question. First-time buyers may need lower down payment paths. Investors may need renovation math to work. Move-up buyers may need to weigh taxes, space, schools, transportation and resale strength. Wandland’s job is to put those variables into sequence before the offer becomes binding.
Financing Tools Can Change the Cash Needed to Buy
Wandland frequently works with FHA financing, VA loans, conventional low down payment options, down payment assistance programs and first-time homebuyer resources depending on the client’s situation. In this article’s frame, those tools matter because they can change how much cash a buyer needs to bring to the table and how much flexibility the buyer has when structuring an offer.
One relevant Illinois option is the Illinois Housing Development Authority Access Home program, offered by the Illinois Housing Development Authority. Access Home offers up to $15,000 in assistance for down payment and closing costs, and IHDA states that the buyer contribution is limited to $1,000 or 1% of the purchase price, whichever is greater. IHDA also offers Access Forgivable, which provides 4% of the purchase price up to $6,000; Access Deferred, which provides 5% up to $7,500 as an interest-free deferred loan; and Access Repayable, which provides 10% up to $10,000 as an interest-free loan repaid over 10 years. (IHDA)
Those programs support Wandland’s true-cost approach because they address the cash-to-close side of the transaction, not just the loan approval. IHDA requires borrowers to meet income and purchase price limits, meet credit requirements, occupy the property as a primary residence and complete homeownership education or counseling before closing. Those requirements make timing important. Buyers need to identify the program before they are deep into a contract, not after they are already trying to solve a closing-cost gap. (IHDA)
FHA and VA financing can also change the upfront-cost conversation for the buyers Wandland serves. FHA loans, insured by the Federal Housing Administration, allow down payments as low as 3.5% for eligible borrowers, according to the Consumer Financial Protection Bureau. VA-backed purchase loans, offered through the U.S. Department of Veterans Affairs, may allow eligible buyers to purchase with no down payment as long as the sales price does not exceed the appraised value and the borrower meets VA and lender requirements. (Consumer Financial Protection Bureau)
Wandland’s value is not in naming every possible program. It is in connecting the right financing path to the buyer’s actual market, property and cost structure. Homebuyer Wallet fits naturally into that process as a discovery tool for buyers who need to identify down payment assistance, closing cost help and homebuyer programs before they assume the only path is more cash saved. The practical benefit is not just finding assistance; it is finding assistance early enough to shape the search, the offer and the closing strategy.
A Better Purchase Comes From Seeing the Whole Deal
Wandland’s philosophy centers on education, strategy and long-term wealth building. He wants clients to understand that real estate can become a tool for financial freedom and generational wealth when approached correctly, but that belief does not lead him into hype. It leads him into details: tax differences, attorney involvement, condition, repairs, financing structure, local inventory and the costs that continue after the keys change hands.
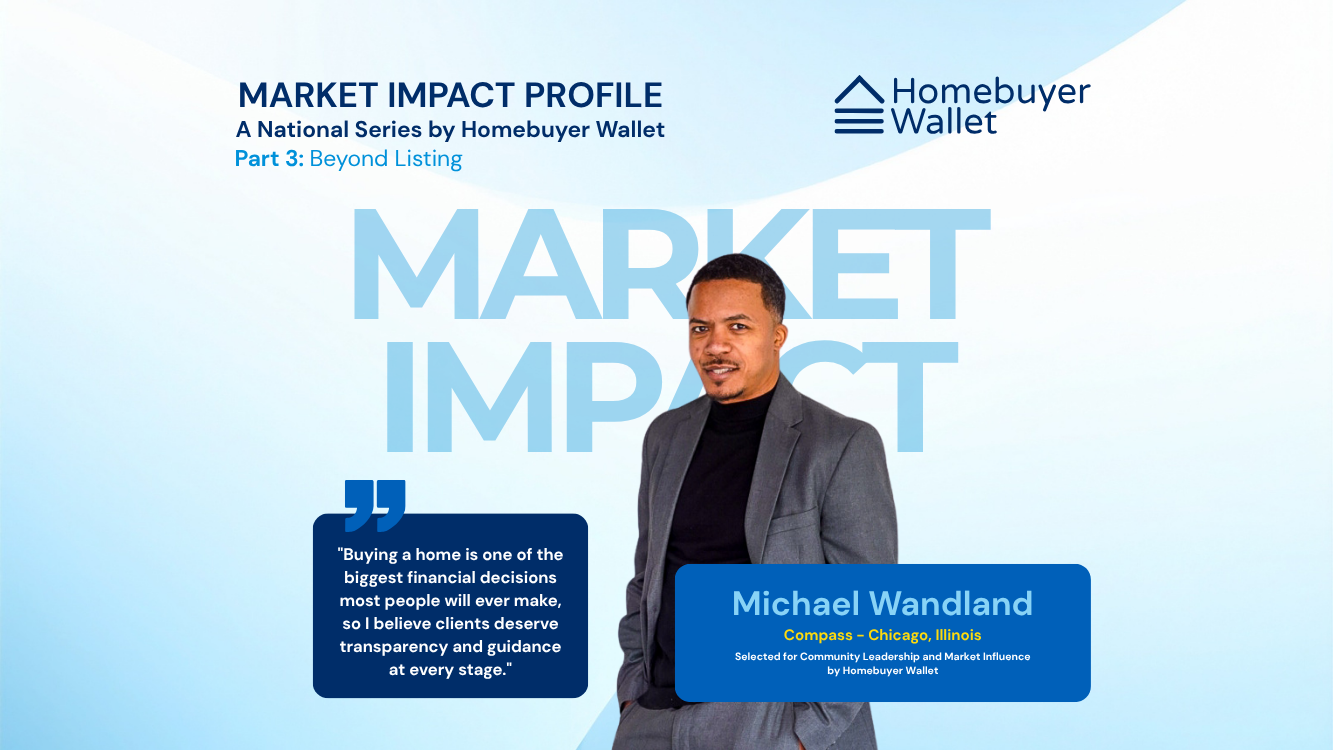
“I focus heavily on education, negotiation strategy, and helping clients fully understand the financial side of the purchase,” Wandland said. “Buying a home is one of the biggest financial decisions most people will ever make, so I believe clients deserve transparency and guidance at every stage.” That is the clearest expression of his role in the Chicagoland market. He is not trying to make the process sound simple. He is trying to make the buyer prepared enough to handle its complexity.
The strongest purchase in Wandland’s view is not always the house with the cleanest photos or the lowest listing price. It is the home where the numbers, condition, financing and long-term ownership picture fit together. In Chicagoland, that means buyers need to understand the full deal before they chase the front door.
Want to connect with Michael? You can follow him on Instagram, Facebook, TikTok, or LinkedIn, or send him an email directly.