
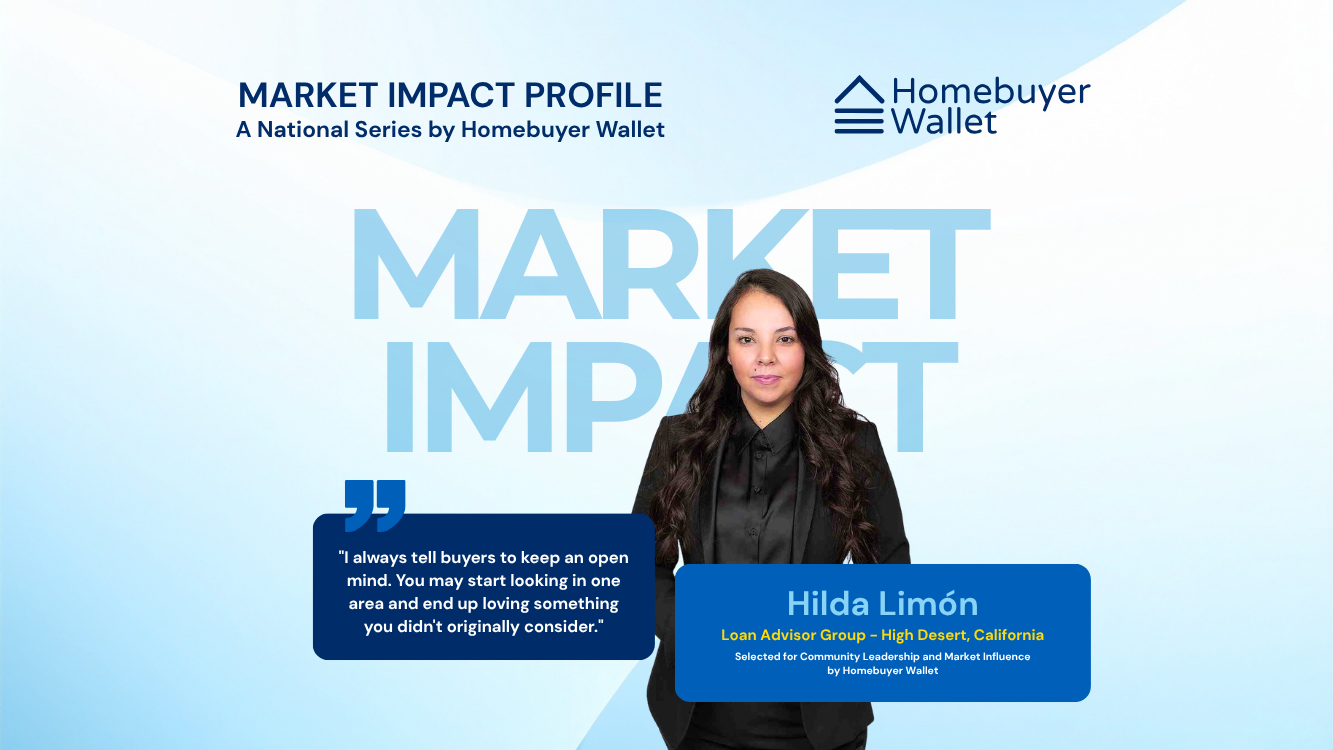
Hilda P. Limón brings experience across real estate, mortgage processing and lending to buyers in California’s High Desert and Inland Empire.
Hilda P. Limón has built her lending career around understanding what happens before, during and after a buyer chooses a home. Since entering the real estate industry in 2017, she has worked as a real estate assistant, moved into mortgage processing and became a Mortgage Loan Originator in 2024. Today, she serves buyers throughout California with strong roots in the High Desert and Inland Empire, where the numbers create a distinct Southern California opportunity: As of August 2026, the median sale price was approximately $440,000 in Victorville, California, and $473,000 in Hesperia, California, compared with $600,000 for an existing single-family home across the Inland Empire and approximately $901,000 statewide.
That price difference is only part of what Limón evaluates with buyers. In the High Desert, many of the clients she works with shop in the $350,000 to $550,000 range, while a typical single-family purchase may fall between $400,000 and $500,000 and provide roughly 1,500 to 2,500 square feet. For Limón, the opportunity is not simply finding a lower purchase price. It is determining how the home, location, monthly payment and long-term goals fit together before a buyer commits.
Local expertise means knowing how financing, property-level expenses, neighborhood options and buyer goals come together before a High Desert buyer commits to a home.
A Career Built From Both Sides of the Transaction
Limón’s understanding of the purchase process developed before she began originating loans. After earning a bachelor’s degree in criminology and criminalistics in Mexico, she returned to the United States in 2017 and began working as a real estate assistant. That role introduced her to the mechanics of a property transaction from the real estate side before she moved into mortgage processing and learned the lending process in greater depth.
By the time she became a Mortgage Loan Originator in 2024, Limón had already spent years seeing what happens when documentation, communication and timing either work together or create friction. That background shapes how she approaches clients now. She does not view financing as an isolated step that begins after someone finds a house; she uses the earlier stages of the process to identify issues, clarify expectations and prepare buyers for what will happen once they enter escrow.
“It’s about being present, communicating, paying attention to the details, and giving every client the same level of care I would want for myself or my family,” Limón said. That attention to detail reflects the way she built her career: first learning how a real estate transaction moves, then learning how the financing behind it gets completed.
The High Desert Creates a Different Southern California Value Equation
Limón serves borrowers throughout California, but the High Desert and Inland Empire form the core of her local market knowledge. In communities such as Victorville and Hesperia, buyers can encounter price points that remain below broader Inland Empire and statewide medians while gaining access to single-family homes, larger lots and a wider range of space.
A typical High Desert purchase for the buyers she serves can involve a single-family home priced between roughly $400,000 and $500,000 with 1,500 to 2,500 square feet. Limón sees buyers drawn to established neighborhoods, newer communities, larger lots and different home styles rather than one uniform housing product. The combination creates room for buyers to weigh how much house they want against the payment and location that work for their lives.
That flexibility matters because Limón’s client base does not fit one borrower profile. She works with first-time buyers, growing families, young professionals, military buyers, move-up buyers, self-employed borrowers, ITIN borrowers and investors. Instead of treating that diversity as a reason to standardize the process, she uses it as a reason to start each purchase with the buyer’s actual circumstances.
Space and Variety Can Change the Search
The High Desert gives Limón room to challenge a buyer’s original assumptions about where and how they should purchase. A client may begin focused on one community, one home style or one set of features, then discover that another area offers a better combination of lot size, living space, payment and long-term usefulness.
“I always tell buyers to keep an open mind,” Limón said. “You may start looking in one area and end up loving something you didn’t originally consider.” She points to the High Desert’s mix of newer communities, established neighborhoods, larger lots, additional land and varied price points as reasons a search can expand rather than narrow once buyers understand what is available.
Her approach keeps lifestyle considerations tied to financial reality. Limón encourages buyers to evaluate the combination of home, location, monthly payment and long-term goals instead of assuming the lowest-priced property or the first preferred neighborhood will automatically produce the best fit. In a market where additional space and different property types can become available within the same general budget, that comparison can materially change what a buyer chooses.
The Listing Price Does Not Tell the Whole Financial Story
Limón’s experience in lending becomes particularly important once a buyer identifies a property. Two homes with similar asking prices can produce different monthly obligations because property taxes, homeowners insurance, HOA charges and special assessments vary from property to property. She reviews those costs with clients before an offer so the financial decision reflects the specific home rather than an assumed payment based only on price.
She also prefers to show buyers an estimate of the total monthly housing payment. Depending on the transaction, that figure can include principal and interest along with property taxes, homeowners insurance, mortgage insurance and HOA costs. The goal is to put the buyer in front of the complete monthly obligation before an offer creates momentum toward a purchase.
“No surprises—we want to know what we’re getting into from the beginning,” Limón said. The line captures the practical value of her local expertise: knowing the High Desert is not only knowing which communities offer more space. It is knowing how an individual property changes the buyer’s numbers once taxes, insurance and other costs enter the calculation.
Preparation Turns Market Knowledge Into Buying Confidence
Limón considers beginning the home search before obtaining a preapproval one of the most common mistakes buyers make. She wants clients to understand their buying power, estimated monthly payment and available financing before they become attached to a property. That preparation gives them defined parameters for the search and puts them in a position to act when the right home appears.
She also directs attention beyond the asking price. Inventory, days on market and seller incentives can change how a buyer approaches a transaction, while available financing can affect what is realistic within the buyer’s budget. Limón uses those conditions alongside the client’s numbers rather than treating the market as a single headline about whether prices are rising or falling.
That preparation becomes more important once a buyer enters California’s title-and-escrow process. A typical purchase transaction in Limón’s market takes about 30 days, although the exact timeline depends on the loan and transaction. The work completed before the offer therefore gives the buyer and lending team more room to focus on executing the purchase instead of discovering fundamental financing issues after the clock has started.
“I want the experience to feel exciting, not overwhelming,” Limón said. Her goal is for clients to understand their options, feel confident in their decisions and know they have someone guiding them throughout the process.
The Right Home Has to Work Beyond Closing Day
Limón’s connection to the work ultimately comes back to the moment a buyer receives the keys. She values being part of what she describes as an important and exciting milestone, but her process begins well before that moment because she wants the purchase to make sense after the transaction is complete.
That is especially relevant in the High Desert, where buyers can compare more than purchase prices. They may be choosing among additional living space, larger lots, newer construction, established neighborhoods and different locations while deciding what payment supports the life they want to build. Limón’s role is to bring those pieces together with the financing and property-specific costs that determine whether the opportunity works in practice.
“I like to meet my clients where they are and build from there,” Limón said. For buyers navigating California’s High Desert and Inland Empire, that means starting with their real financial position, understanding what each property will actually cost and using the market’s variety to find a home that fits both the numbers and the next stage of their lives.
Want to connect with Hilda? You can follow her on Instagram, Tiktok, Facebook, or send her an email directly.