
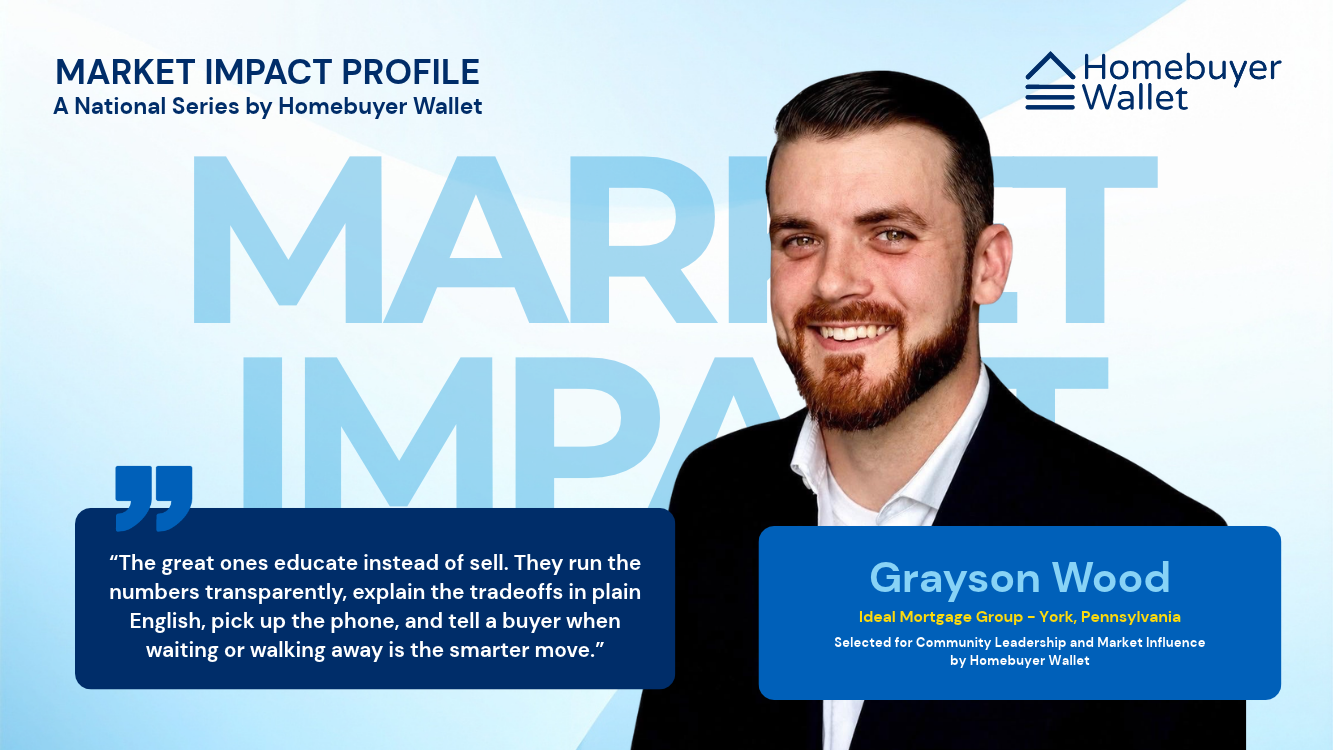
Grayson Wood of Ideal Mortgage Group brings personal experience, straightforward mortgage education and local insight to first-time buyers across South Central Pennsylvania.
Grayson Wood purchased his first home in March 2026 using a mortgage that required no down payment. A week after he moved in, his employer had no work hours available for him, and he lost his life savings to a brokerage scam. The experience exposed how quickly financial security could change, even after reaching a major milestone like homeownership. Now a loan officer with Ideal Mortgage Group, Wood draws on those experiences to help buyers understand their financial decisions and pursue homeownership across Adams, York, Lancaster and Dauphin counties in Pennsylvania.
Wood’s path into mortgage lending began outside the financial industry. Before becoming a loan officer, he worked in in-home care for people with mental disabilities, often putting in 80-hour workweeks. That experience taught him to communicate complicated information with patience and clarity, skills he now brings to conversations with first-time buyers who may be unfamiliar with mortgage terminology, financing options and the financial responsibilities of owning a home.
A Career Change Rooted in Financial Reality
Wood’s transition into lending followed a difficult period in his personal life. After purchasing his home through a U.S. Department of Agriculture loan with 0% down, he faced an unexpected loss of employment hours and significant financial losses. His sister, who also works as a loan originator, encouraged him to explore the mortgage industry, introducing him to a profession that connected his personal experience with his ability to help others navigate complicated decisions.
Rather than building his approach around selling loans, Wood focused on the information he believed buyers needed before making financial commitments. His experience purchasing a home showed him that affordable financing opportunities existed, while the financial setbacks that followed reinforced the importance of understanding household finances beyond the initial purchase.
“I’ve been learning the craft since, and I teach it the way I wish someone had taught me: plain English, real numbers, no fluff,” Wood said.
His background in caregiving also shaped how he approaches people who need additional guidance. Working with individuals with disabilities and their families required him to explain unfamiliar situations clearly, listen carefully and recognize when someone needed more information. Those habits now influence how he communicates with mortgage clients, particularly buyers entering the housing market for the first time.
Wood is also a single father to a 5-year-old, and his personal experience reinforces his focus on the practical realities of household finances. His professional approach reflects an understanding that purchasing a home involves more than qualifying for a mortgage. Buyers must also consider how their payments fit into their daily lives and long-term responsibilities.
Clear Numbers Before Bigger Loans
Wood’s lending philosophy begins with education rather than the maximum loan amount a borrower can obtain. When working with clients, he encourages them to identify a monthly housing payment they can comfortably manage, then determine what purchase price fits within that limit. This approach makes the ongoing financial commitment the starting point instead of treating the lender’s maximum approval amount as the buyer’s target budget.
“I’d rather a buyer understand exactly what they’re signing and why than push them into the biggest loan they qualify for,” Wood said.
Education-first lending means helping borrowers understand their financing choices and financial obligations before committing to a home purchase.
Wood applies that principle by explaining mortgage terms, reviewing financing options and discussing the tradeoffs that can affect a buyer’s monthly payment. He believes effective loan officers should remain accessible throughout the process and be willing to tell clients when postponing a purchase or walking away from a property is the more responsible financial decision.
“The great ones educate instead of sell,” Wood said. “They run the numbers transparently, explain the tradeoffs in plain English, pick up the phone, and tell a buyer when waiting or walking away is the smarter move.”
His educational approach also reflects his own introduction to homeownership through a zero-down-payment mortgage. Wood knows firsthand that buyers do not necessarily need years of savings to make a purchase, but he emphasizes that understanding the full financial obligation matters just as much as finding a way to get into a home.
Pennsylvania Roots Shape the Market Focus
Wood’s connection to South Central Pennsylvania extends beyond his lending career. He grew up in the region and continues to appreciate its combination of working communities, outdoor recreation and access to larger employment centers. His familiarity with the area shapes his interest in helping residents purchase homes without necessarily moving to higher-priced metropolitan markets.
“It’s home. I grew up around here, I fish the Susquehanna, and I like that it’s a place where regular working people can still actually afford to buy a home,” Wood said.
His primary service area includes Adams, York, Lancaster and Dauphin counties, with York County serving as the central anchor. The region offers access to Harrisburg, Pennsylvania; Baltimore, Maryland; and Washington, D.C., allowing some residents to maintain connections to major employment markets while living in communities with comparatively lower housing prices.
Wood sees that geographic position as an important advantage for local buyers and people relocating from more expensive areas. Remote workers and commuters can explore housing options across smaller Pennsylvania communities without necessarily giving up access to larger metropolitan economies.
The region’s character also contributes to its appeal. Established boroughs, rural townships and suburban developments offer different living environments within the same broader housing market. For Wood, those differences create opportunities to work with buyers whose priorities range from affordability and commuting convenience to outdoor access and neighborhood character.
An Affordable Market With More Than One Path to Ownership
Wood’s typical clients shop for homes priced between $230,000 and $330,000, a range that reflects the affordability he values in South Central Pennsylvania. He identifies York County as a central example, citing a median sold price of approximately $310,000, an increase of 7% from the previous year, according to figures he attributes to the Realtors Association of York and Adams Counties.
Neighboring counties offer different price points. Wood places the median home price near $350,000 in Adams County and $385,000 in Lancaster County, compared with a national median of approximately $429,000. That puts York County’s reported median roughly $119,000 below the national figure, illustrating why Wood considers the region an attainable housing market for working households.
He also points to regional housing inventory reaching a five-year high, giving buyers more properties to consider. That expanded selection matters in a market where the available housing varies significantly across municipalities, from older borough properties to detached homes in suburban neighborhoods.
“The mix. You’ve got genuinely rural townships where USDA 0% down works, older boroughs with affordable rowhomes and twins, and suburban developments, all within commuting distance of Baltimore, Harrisburg, and D.C.,” Wood said.
A recent transaction in McSherrystown, Pennsylvania, illustrates the kind of housing available within his clients’ typical budgets. The buyers purchased a detached single-family home for $300,000, securing a property with three bedrooms, two bathrooms and 1,953 square feet of above-grade living space. The purchase reflects the combination of price and property size that Wood sees attracting buyers to the region.
Property location also influences the financing opportunities Wood can present. Some rural townships qualify for mortgages through the U.S. Department of Agriculture’s Single Family Housing Guaranteed Loan Program, which provides 100% financing for eligible borrowers and properties. Wood’s own experience purchasing a home with no down payment makes that option particularly meaningful to his work with buyers who may have sufficient income for a mortgage but limited savings for an upfront down payment.
Financial Education Extends the Opportunity to First-Time Buyers
First-time buyers make up the largest share of Wood’s clientele, although he also works with young professionals and move-up buyers. Many of the borrowers he encounters are comparing homeownership with rising rental costs, often discovering that a potential mortgage payment may be close to what they already pay their landlords.
Wood approaches those conversations by examining the complete monthly housing expense rather than focusing exclusively on principal and interest. Property taxes and homeowners insurance vary across Pennsylvania municipalities and school districts, making the full payment calculation essential when determining whether a particular home fits a buyer’s finances.
His work with the Pennsylvania Housing Finance Agency, or PHFA, provides additional options for borrowers who might otherwise assume purchasing a home requires a substantial down payment. The agency’s Keystone Home Loan program offers eligible buyers access to fixed-rate mortgage financing, while its Keystone Forgivable in Ten Years Loan Program, commonly known as K-FIT, can provide down payment and closing cost assistance of up to 5% of the purchase price, forgiven over 10 years.
For a qualifying buyer purchasing a $300,000 home, assistance equal to 5% would represent $15,000 toward eligible upfront expenses. Wood views these opportunities as particularly important in his market, where buyers may have the income to support a monthly mortgage payment but lack the savings they believe are necessary to begin the process.
He also works with conventional financing options such as Fannie Mae’s HomeReady Mortgage, which allows eligible borrowers to make down payments as low as 3%. Together with PHFA financing and USDA loan options, these products allow Wood to explain why a 20% down payment is not a universal requirement for homeownership.
His commitment to education extends beyond individual mortgage consultations. Under the name @GraysonDoesMortgages, Wood publishes free mortgage and personal finance content on TikTok, Instagram, YouTube and Facebook. His educational material focuses on the financial details consumers may overlook, reflecting his belief that better information helps people make more deliberate decisions.
“Everything I teach publicly is the same stuff I walk my own clients through,” Wood said.
That consistency connects Wood’s personal journey with the work he performs today. After experiencing both the opportunity of purchasing a home with no down payment and the uncertainty of unexpected financial losses, he entered mortgage lending with a particular interest in helping buyers understand their choices.
Across South Central Pennsylvania, where home prices remain comparatively accessible and financing options vary by household and property, Wood sees education as a way to help more buyers recognize what is possible. His goal is not simply to show clients that they can qualify for a mortgage, but to help them understand whether the home they choose makes sense for their financial lives.